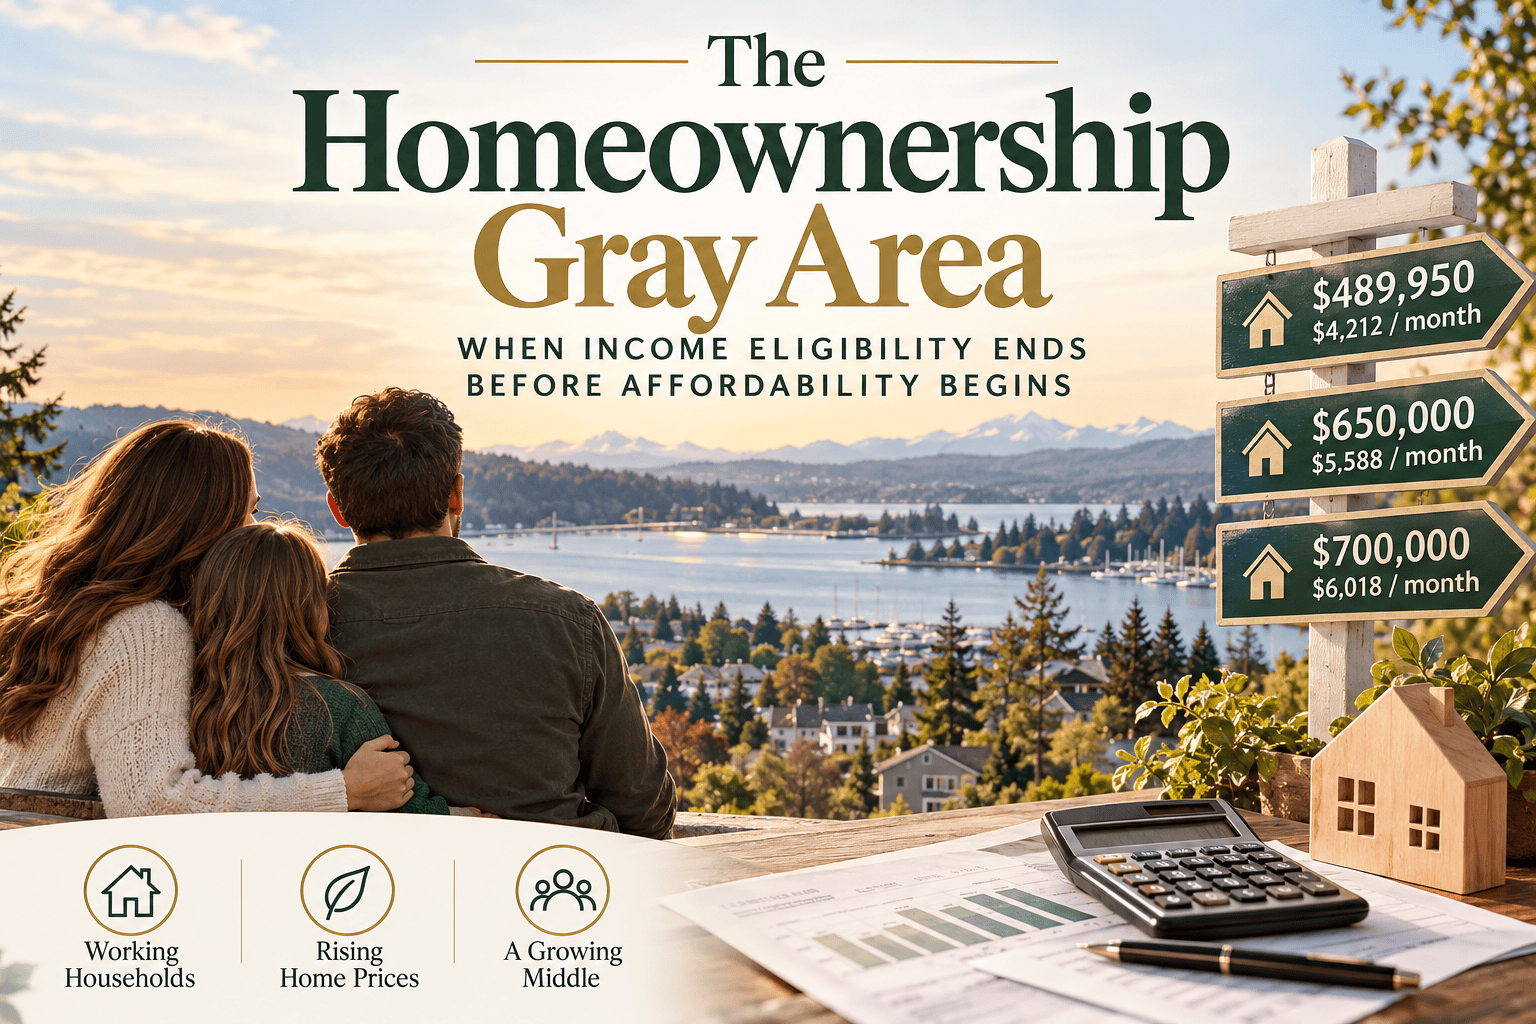
The Homeownership Gray Area
What happens when a working household earns too much for some forms of housing assistance, but still does not earn enough to reasonably afford homeownership in the local market?
When Income Eligibility Ends Before Affordability Begins
Some working households are caught between two housing realities. Their incomes may place them above traditional affordable housing limits, while market-rate homeownership remains beyond what their income can reasonably support.
A household can earn $100,000 or even $120,000 a year and still face a significant gap between its income and the cost of sustainable homeownership.
What Does 80% AMI Actually Mean?
Area Median Income, or AMI, is commonly used by housing programs to establish income eligibility. One frequently used benchmark is 80% of AMI, although requirements vary by program and household size.
Source: U.S. Department of Housing and Urban Development, FY2025 income limits. Kitsap figures correspond to the Bremerton–Silverdale–Port Orchard area; Pierce figures correspond to the Tacoma area. Individual program requirements may vary.
What About Lower-Priced Homes?
Lower-priced homes do appear in the market, but there are fewer of them, and some require substantial repairs or rehabilitation. Roofing, electrical systems, plumbing, foundations, water damage, mold or heating systems can add significant costs after purchase.
For a household already stretching to cover a down payment and closing costs, a lower purchase price does not necessarily mean the home is realistically affordable. The goal is not simply to find the cheapest house available, but to examine reasonably livable homes at realistic market prices.
What Homeownership Can Cost
Kitsap County’s median sale price was approximately $620,415 for the three months ending August 2026. To illustrate affordability on both sides of that median, this analysis uses a $550,000 home and a $700,000 home.
Three months ending August 2026
Using 5% down and the same mortgage-cost assumptions throughout the comparison, the estimated monthly ownership costs are:
Estimated monthly ownership costs include principal and interest, estimated property taxes, homeowners insurance and mortgage insurance. HOA dues are not included. Median sale-price source: Redfin, Kitsap County housing-market data through August 2026.
Gross Income Is Not Spendable Income
AMI and annual salary figures are based on gross income, but households do not have their full gross income available for housing and everyday expenses. Federal income taxes and Social Security and Medicare taxes reduce take-home pay before the mortgage, healthcare, food, transportation, utilities and other household costs are paid.
Beyond taxes and housing, a representative family of three may also face ordinary recurring expenses such as:
| Monthly household expense | Illustrative cost |
|---|---|
| Family health insurance premium | $600 |
| Groceries | $900 |
| Used-car payment | $542 |
| Auto insurance | $175 |
| Gas | $250 |
| Electricity | $150 |
| Water, sewer & garbage | $175 |
| Internet | $80 |
| Cell phones | $120 |
| Household & personal necessities | $250 |
| Basic home-maintenance reserve | $300 |
| Total ordinary expenses beyond housing | $3,542/month |
These figures are illustrative. Household expenses vary, and the $600 health-insurance amount represents an example employee contribution for family coverage rather than a universal premium.
What Is Actually Left?
To illustrate the effect of taxes, the examples below use estimated monthly income after federal income tax and employee Social Security and Medicare taxes. Actual take-home pay varies by household.
Household Earning $100,000 Per Year
Household Earning $120,000 Per Year
And That Is Not the Entire Budget
Childcare, debt payments, retirement contributions, emergency savings, major vehicle or home repairs, children’s activities and discretionary expenses such as an occasional family vacation are not included above. Any remaining income would also have to absorb those costs.
A Look Beyond Kitsap County
Nearby Gig Harbor, located in Pierce County, illustrates how much higher prices can climb in the surrounding housing market.
Redfin reported a median Gig Harbor sale price of approximately $991,344 for the three months ending August 2026. Yet the affordability gap is already visible without using a nearly $1 million home in the household calculations above.
Source: Redfin, Gig Harbor housing-market data through August 2026.
The Homeownership Gray Area
Lower-income housing programs remain essential. But working households can move above traditional income limits while sustainable market-rate homeownership remains out of reach.
Starter Home Initiative is exploring smaller thoughtfully designed homes, Community Land Trust ownership and shared community resources as ways to bring homeownership costs back into proportion with what working households actually earn.
Starter Home Initiative exists to help close that gap.