The Mortgage Trap
The Mortgage Trap
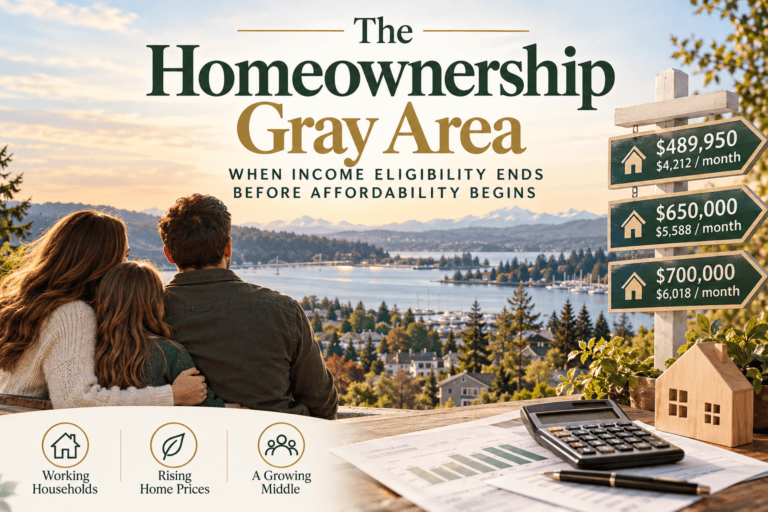
They qualified. They bought the house. Now they cannot afford the life that comes with it.
They Finally Became Homeowners
Two parents earning $30 and $27 per hour worked full-time, paid off their car and consumer debts, and saved $50,000 for a down payment.
After years of renting, they found a modest, move-in-ready three-bedroom home in Port Orchard. Then the asking price dropped.
With their savings available for the down payment, the family purchased the home with a $450,000 mortgage.
With no other qualifying monthly debt, their proposed $4,208 housing payment represented approximately 42.6% of gross monthly income.
They were approved, closed on the purchase, received their keys, and moved into their home.
1. The Cost of Living in Their Home
Monthly housing payment
Illustrative 30-year mortgage at 7.375%. Bars compare each item with the principal-and-interest amount.
Their estimated take-home pay is $7,700 per month. They also have a three-year-old daughter who needs full-time childcare so both parents can work.
Their actual homeowner budget
$7,700 take-home income minus $8,108 in expenses. Living expenses exclude childcare, health insurance, and car-loan payments. Bars are scaled against housing.
They are already house-poor. There is no room in this budget to rebuild savings, cover home repairs, or absorb an emergency.
2. Months After Moving In, Their Car Breaks Down
The car was fully paid off before the family applied for its mortgage. They received their loan, closed on the house, and had been living in their home for months when the vehicle broke down.
With their savings committed to the down payment and no ability to buy another car outright, they financed a replacement.
The new payment is $370 per month. This expense arose after they were already homeowners.
How one setback changes the budget
The two bars show the components of the final $778 shortfall. The car loan was incurred after the family moved into the home.
Their new monthly budget
| Take-home income | $7,700 |
| Housing | −$4,208 |
| Living expenses | −$1,800 |
| Childcare | −$1,500 |
| Health insurance | −$600 |
| Replacement car payment | −$370 |
| Monthly balance | −$778 |
3. When Owning a Home Means Having No Financial Freedom
To keep up, one parent may need a second job or additional hours. That means more time working and less time with their daughter. Even then, extra income may go straight toward the monthly deficit instead of savings or family needs.
The family owns a home but cannot comfortably afford ordinary setbacks. They may postpone repairs, cut necessary expenses, or rely on additional borrowing.
4. Why Not Just Sell?
Selling is possible, but it is not as simple as getting their $50,000 down payment back and starting over.
The home must sell, the mortgage must be paid off, and selling expenses—including any agreed real estate-agent compensation and other transaction costs—must be covered.
What remains depends on the sale price, outstanding loan balance, and costs. They might recover some equity, all of it, or less than they originally invested.
Meanwhile, they still need somewhere to live. If they return to renting, they may need funds for a deposit, moving expenses, and the first month’s rent—money they have struggled to save while carrying the mortgage.
Buying another comparable home may not solve the problem if its monthly cost is similarly unaffordable.
Selling can be a way out, but it may mean leaving the home they worked for, losing part of their original investment, and beginning the homeownership journey again.
The Mortgage Trap
This family did not enter homeownership with an unpaid car loan or mounting consumer debt. They worked, saved, qualified, and purchased their home.
Yet essential expenses left them in a monthly deficit from the beginning. One ordinary breakdown made it worse.
The mortgage trap is not simply the difficulty of buying a home. It is becoming a homeowner only to discover that keeping the home requires sacrificing savings, financial security, and potentially time with family.
Attainable Homeownership. Sustainable Communities.
Starter Home Initiative is working toward modest, attainable homes for working households priced out of conventional homeownership.
The goal is to make ownership possible without requiring families to sacrifice the financial stability they worked so hard to achieve.
The family and property are fictional. Both parents work 40 hours weekly at $30 and $27 per hour. Estimated take-home income is $7,700 per month.
The mortgage illustration assumes a $500,000 purchase, $50,000 down payment, $450,000 loan, 30-year term, and 7.375% interest rate. The $4,208 housing cost includes the $98 HOA.
The $1,800 living expenses, $1,500 childcare, $600 health insurance, and subsequent $370 car payment are illustrative. The $50,000 is assumed available for the down payment after any separate closing costs. No emergency or home-maintenance reserve is included.
Mortgage approval is not guaranteed solely by the illustrated debt-to-income ratio. Sale proceeds are not guaranteed, and this story does not assume the family has sold or lost its home.